Life insurance built for people who work with their hands
Life insurance for people who work with their hands
Free to useNo obligationLicensed agents only
Oilfield, electrical, roofing, welding, mining or the plant floor: answer a few quick questions and we'll match you with a licensed agent who knows how carriers look at your trade. The service is free.
- Coverage you own, which doesn't end when a job or contract does
- Hazardous trades may still qualify for coverage
- A free match with a licensed agent, not a sales call center
Why tradespeople need their own coverage
Workers' comp only covers work deaths
Workers' compensation death benefits generally apply only when a death is caused by the job. A car wreck on a Sunday, a heart attack at home or an illness isn't a comp claim, so your family would get nothing from it.
Union and employer plans can end
Group life through a union or employer is usually tied to that job or membership. It can end or shrink when you change contractors, get laid off or retire. Converting it is sometimes possible, but often at a higher cost.
Dangerous work can still be covered
Carriers underwrite hazardous occupations differently. Some charge more or add a flat extra charge, while others weigh your trade less heavily. A licensed agent can compare carriers instead of stopping at the first no.
Your paycheck carries the household
If your income stopped, a term policy could help cover the mortgage, truck payments and everyday bills while your family adjusts. Coverage is sized to what they would actually need.
- 01
Oilfield hand on a rotation
Rig, well-service and pipeline workers can work long hitches in hazardous conditions. An agent can find out which carriers insure your specific role and how offshore or remote work is rated.
- 02
Lineman or utility worker
High-voltage work and working at heights are underwriting questions, not automatic declines. An agent can compare how carriers treat line work before you apply.
- 03
Roofer working at heights
Roofing is one of the more dangerous trades. Some carriers price it with a flat extra charge, and others may not. Shopping several carriers can matter more than it does for desk jobs.
- 04
Union electrician near retirement
Coverage through your local or employer may end or drop when you retire. Getting your own policy before you leave, while you're still working and healthier, can keep your family protected.
- 05
Self-employed contractor
If you run your own crew or work 1099, there's no group plan behind you. A policy you own can protect your family and help cover business debts like equipment loans.
Life insurance for blue-collar and trade workers
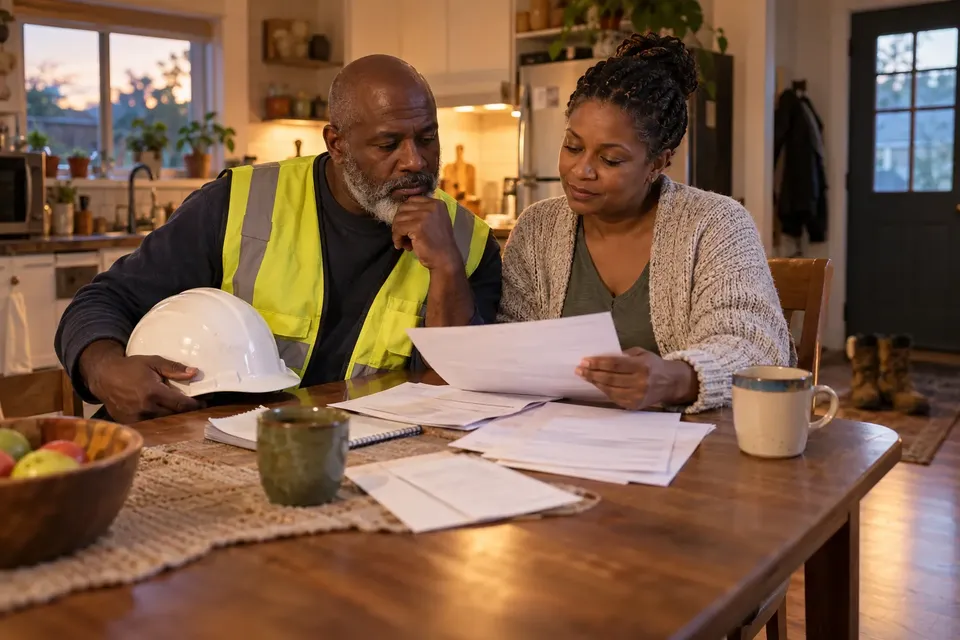
Workers' Comp Death Benefits vs. Life Insurance: What Each Pays
Workers' comp death benefits pay only when a death is caused by a work injury or illness, and state law decides who gets paid, how much, and for how long. Life insurance pays the amount you choose to the people you name for most causes of death, so it fills the gaps workers' comp leaves.
Editorial Team · September 30, 2026
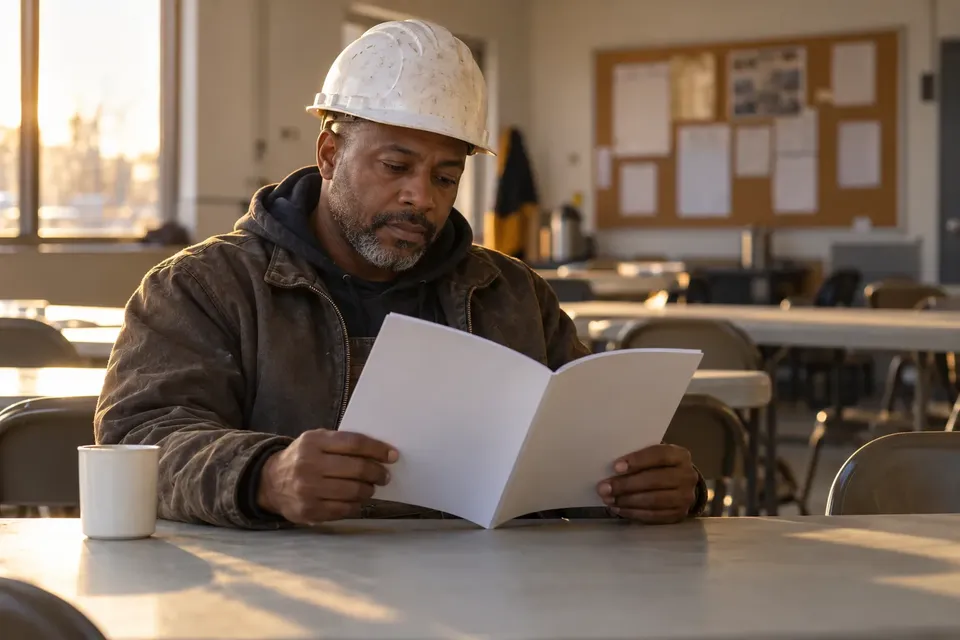
Union Life Insurance Benefits: What Ends When You Retire
Union life insurance is usually group term coverage paid for through your employer or a union benefit fund, and it typically ends or shrinks when you leave covered work, lose eligibility or retire. Many group policies let you convert to an individual policy without health questions if you apply within a short window, so read your plan documents well before your last day.
Editorial Team · September 30, 2026
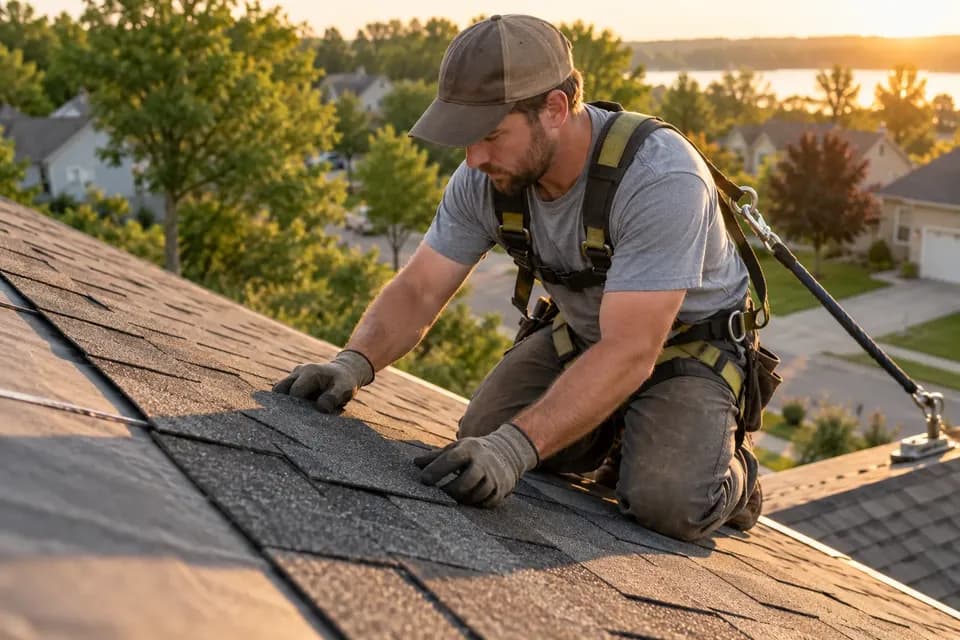
Most Dangerous Jobs in America: 2024 BLS Fatality Data
Logging workers had the highest fatal work injury rate among the occupations the Bureau of Labor Statistics highlighted for 2024, at 110.4 deaths per 100,000 full-time equivalent workers, followed by fishing and hunting workers (88.8) and roofers (48.7). Driver/sales workers and truck drivers had the most deaths of any occupation shown, with 950.
Editorial Team · September 30, 2026
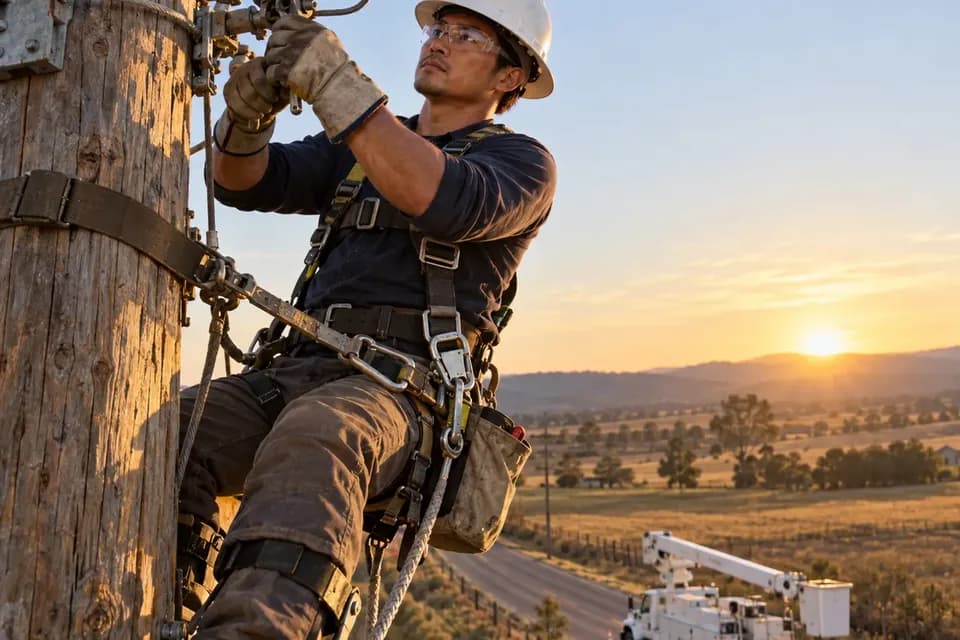
Life Insurance for High-Risk Jobs: Flat Extras and Table Ratings
You can often get life insurance with a dangerous job, but the insurer may charge more through a flat extra or a table rating, exclude a specific activity, or in some cases decline. Because each insurer has its own occupation rules, describing your duties precisely and comparing several companies can make a real difference.
Editorial Team · September 30, 2026
Life Insurance for Blue-Collar Workers: What Trades Should Know
Many blue-collar and trade workers can buy regular term or whole life insurance, though insurers ask about your job and may charge more for hazardous duties. Group coverage through an employer or union is often limited and usually ends when you leave, so many workers add a policy they own.
Editorial Team · September 30, 2026
Best Life Insurance for Blue-Collar Workers (2026)
The best life insurance for a blue-collar worker depends on what you need most: State Farm publishes a disability premium waiver and sells through local agents, Foresters Strong Foundation is non-medical term with living benefits included, and Banner Life and Protective offer terms up to 40 years. New York Life's term carries the top AM Best rating in this group and can be converted to permanent coverage, even if you change jobs.
Editorial Team · September 30, 2026
Common questions
Can I get life insurance if I work a dangerous job?
Usually, yes. Many carriers insure oilfield workers, linemen, roofers, miners and other hazardous trades. Your occupation can affect your rate: some carriers add a flat extra charge per $1,000 of coverage, while others treat certain trades more favorably. Comparing several carriers through a licensed agent is the best way to find out what you may qualify for.
Doesn't workers' comp already cover my family if I die?
Only if the death is work-related. Workers' compensation death benefits generally apply when a death arises out of the job, and the amounts are set by state law. Deaths from off-the-job accidents, illness or natural causes aren't covered by comp. Personal life insurance pays regardless of where or how you die, subject to the policy terms.
What happens to my union or employer life insurance when I retire or leave?
It often ends or shrinks. Group life is usually tied to your job or membership. Some plans let you convert or port coverage when you leave, but converted coverage can cost more. Check your plan documents or ask your benefits administrator, and consider owning a policy that stays with you no matter where you work.
How much life insurance does a tradesperson need?
A common starting point is enough to replace several years of income, plus your mortgage balance, other debts and final expenses. Subtract savings and any coverage you'll keep. For example, a hypothetical worker earning $70,000 with a $200,000 mortgage might look at $500,000 or more. An agent can help you size it to your own budget.
Is term or whole life better for blue-collar workers?
Term life is usually the most affordable way to protect a family during working years, such as while a mortgage is being paid off or kids are at home. Whole life and other permanent policies cost more but last for life and can build cash value. Many people start with term and add a smaller permanent policy for final expenses.
Will I need a medical exam?
Not always. Some carriers offer policies without a medical exam, depending on your age, health and the amount of coverage. Larger policies are more likely to need an exam or lab work. A licensed agent can tell you which options fit your situation before you apply.
Is this service really free, and are you an insurance company?
Yes, it's free to use, and no, we aren't an insurer or agency. We're a matching service that connects you with a licensed agent who can compare options. Nothing is sold through the quiz, and you're never obligated to buy. Any policy, price or approval comes from the carrier after you apply.